 38
/ 3
Min Read


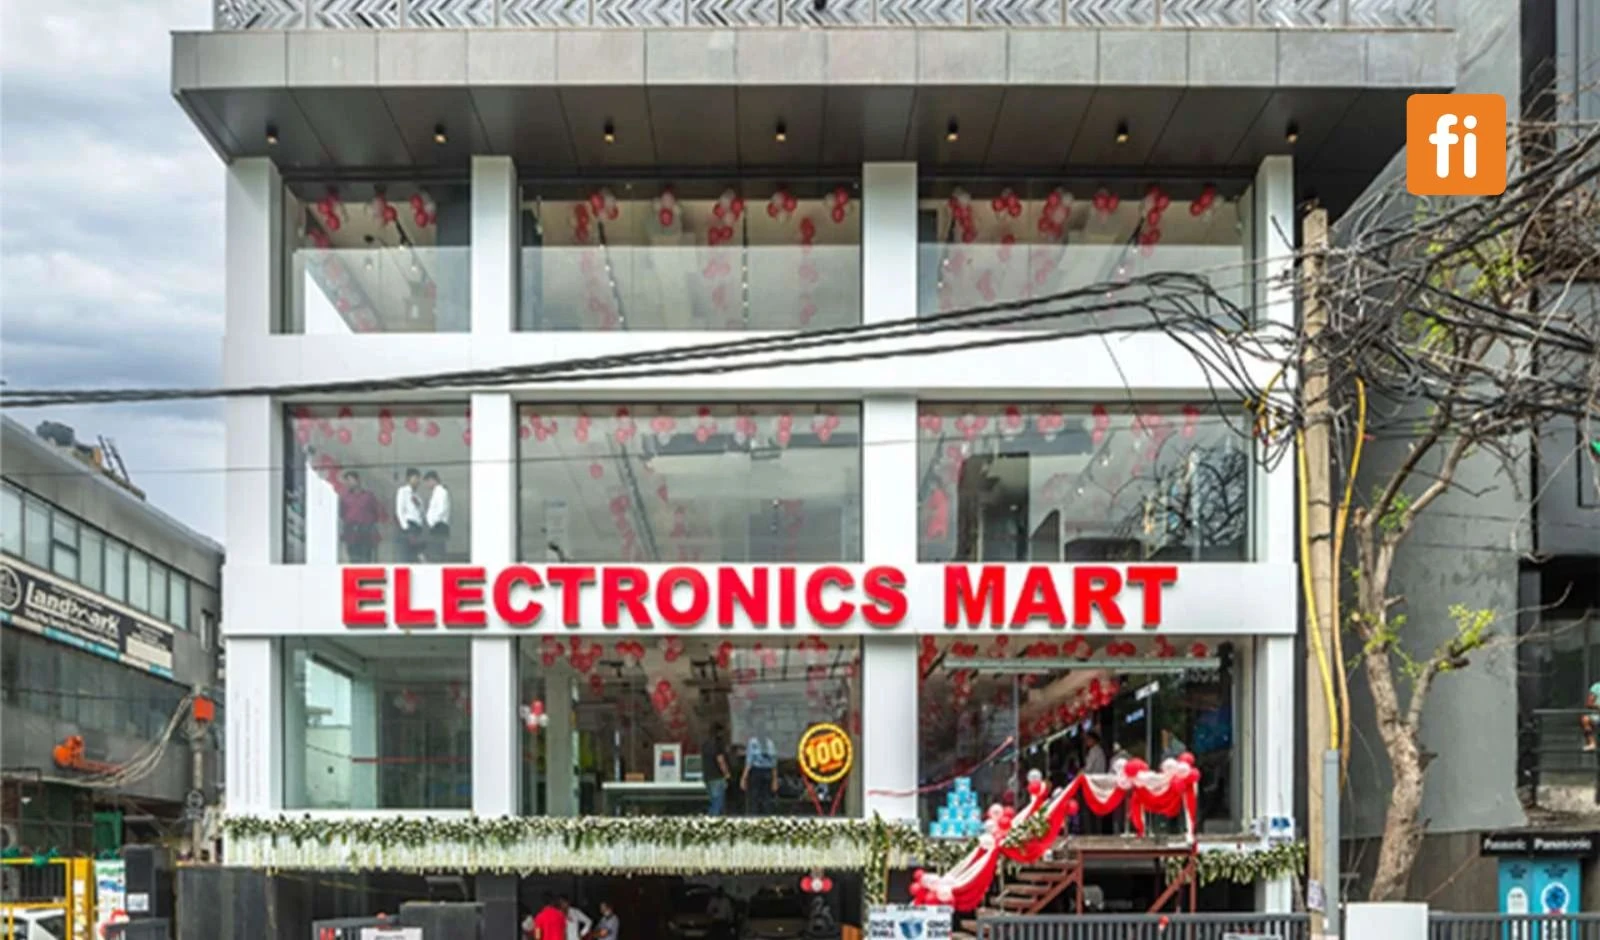
Electronics Mart India Limited (EMIL) reported a 30 percent year-on-year increase in revenue from operations to Rs 4,319 crore in H1 FY27, ended September 30, 2026. EBITDA nearly doubled, rising 93 percent to Rs 369 crore, while profit after tax (PAT) increased 326 percent to Rs 161 crore.
For Q2 FY27, revenue grew 19 percent to Rs 1,900 crore, while PAT rose 149 percent to Rs 40 crore. EBITDA increased 61 percent to Rs 131 crore, with its margin expanding 180 basis points to 6.9 percent. Same-store sales growth (SSSG) stood at 16.5 percent for the quarter and 27.5 percent for H1.
The retailer's network reached 229 stores across more than 100 cities after six net additions during the first half. Its South Cluster recorded 28 percent revenue growth in H1, while the North Cluster posted 36 percent growth.
The company also reported improvements in working capital, with its cycle reducing from 77 days to 61 days. Pre-Ind AS operating cash flow stood at Rs 304 crore during H1.
Karan Bajaj, CEO of EMIL, said, “H1 FY27 has been a robust half for EMIL, with every key metric moving in the right direction. Revenue grew 30 percent to Rs 4,319 crore, gross profit rose 49 percent with margins expanding 210 bps to 16.4 percent, EBITDA nearly doubled to Rs 369 crore at an 8.6 percent margin, and PAT rose over 4x to Rs 161 crore. Q2 is seasonally a softer quarter for consumer durables. Despite this, we delivered 19 percent revenue growth, SSSG of 16.5 percent and a 180 bps expansion in EBITDA margin to 6.9 percent, with growth broad-based across categories. Mobiles grew 31 percent, driven by new smartphone launches and continued traction in existing models, while air conditioners grew 53 percent even in the off-season. Premium and emerging categories such as built-in appliances, dishwashers, tablets and wearables also delivered strong double-digit growth, and our average ticket size rose 15 percent, reflecting our strength in premium categories.”
“The South market remains a scaled, profitable engine for us, with revenue up 28 percent in H1 and EBITDA margin up 320 bps to 9.3 percent. The North cluster is on a similar path: revenue grew 36 percent in H1 and EBITDA margin rose to 3.4 percent from 1.0 percent as our stores mature and scale. More than half of our network is under four years old, so we expect margins to keep improving as a better product mix and operating leverage take effect. We are on track to enter West Bengal, our next growth cluster, and we are confident it will add to our growth. Our focus on working capital continues to pay off, with pre-Ind AS operating cash flow growing to Rs. 304 crores. With festive demand off to a strong start and a solid first half behind us, we remain firmly on track to deliver growth, while continuing to invest in the customer experience that has underpinned EMIL’s growth for over four decades,” he added.
EMIL is preparing to enter West Bengal as its next growth market. The company expects store maturity, product mix improvements and operational efficiencies to support its expansion and profitability.